To buy bitcoin in Singapore, open an account with a provider licensed by the Monetary Authority of Singapore (MAS) for digital payment token service, confirm the licence in the MAS Financial Institutions Directory, complete the identity check and the risk awareness assessment, fund the account, and place the order. Bitcoin is a digital payment token (DPT) under the Payment Services Act 2019, so a business that buys or sells it for customers in Singapore needs a licence. The rules protect how a provider holds your assets. They do not protect you from a fall in the price, and MAS says you can lose everything you put in.

Step 1: Check that the provider is licensed
Under the Payment Services Act, "digital payment token service" is one of seven regulated payment services. MAS describes it as buying or selling DPTs (commonly known as cryptocurrencies), or providing a platform that lets people exchange them. A firm providing this service in Singapore must hold a licence or fall under an exemption in the Act; banks licensed under the Banking Act are among the exempt providers.
There are two licence types for this service:
- Major payment institution: may conduct payment services without the transaction thresholds set in the Act.
- Standard payment institution: must stay below those thresholds.
How to check a provider:
- Search for the company's legal name in the MAS Financial Institutions Directory. The entry shows the licence type and the activities the firm is authorised to carry out. Look for "Digital Payment Token Service".
- Check the name against the MAS Investor Alert List. MAS describes it as a non-exhaustive list of persons unregulated by MAS that may have been wrongly perceived as licensed. A name missing from that list is not proof that a firm is regulated.
- Reach the provider through the official contact details shown in its directory entry or on its own website, not through a link in an unsolicited message. MAS warns about fraudulent websites and chat groups that promise high returns.
MAS tells consumers not to deal with unregulated entities, including those based overseas.
Step 2: Pass the identity check
DPT service providers must carry out customer due diligence under MAS Notice PSN02. Expect to give:
- your full name and a unique identification number, such as an NRIC or passport number
- your residential address
- your date of birth
- your nationality
The provider has to verify these details against reliable, independent documents, data or information. If you open the account online, the checks must be at least as strict as for a face-to-face meeting, so expect to photograph your ID and, in many cases, take a selfie or video for a biometric match.
Step 3: Take the risk awareness assessment
Since 19 June 2025, MAS guidelines (PS-G03) expect a provider to assess whether an individual retail customer understands the risks of its DPT services before serving them, and to tell the customer the result. If the assessment finds you lack sufficient knowledge, the provider should not provide the service.
The topics include:
- prices are highly volatile and can fall to zero
- you may be unable to sell because of illiquid markets, outages or cyber-attacks
- tokens can be lost through fraud, theft or the loss of private keys
- risks in how the provider or a third party holds customer assets
- conflicts of interest within the provider
- extra risks of dealing with unregulated providers based outside Singapore
Step 4: Fund the account
Each provider sets its own funding methods; Singapore dollar bank transfer is the usual route. One method is ruled out: under PS-G03, a DPT service provider should not accept payments from a retail customer made with a credit card or charge card issued in Singapore. This includes using such a card to top up an account that is later used to buy tokens.
The same guidelines say a provider should not lend to a retail customer to buy or keep holding DPTs, should not offer margin or other leveraged DPT trading, and should not offer DPT derivatives to retail customers. The Payment Services Act separately bars licensees from granting credit facilities to individuals in Singapore.
Step 5: Compare fees before you buy
Fee structures differ by provider. The common types are:
- Trading fee: a commission on each buy or sell order.
- Spread: the gap between the buying and selling price, which can be the main cost on a simple "buy" button.
- Deposit and withdrawal fees: charges for moving Singapore dollars in or out.
- Network or withdrawal fee: charged when you send bitcoin to an outside wallet.
- Custody fees: charges for holding your assets, where a provider applies them.
PS-G03 expects providers to disclose all applicable fees and costs for safeguarding customer assets, and to send a monthly statement that includes the financial charges and credits on your account. Read the fee page and the terms before your first order.
Exchange or your own wallet: where to keep bitcoin after buying
Answer two questions to see what each custody option involves and what it risks.
One guide's wallet advice covers large or long-term holdings. Is your holding large or long-term?
- Yes → next question
- No → Bitcoin stays with the exchange
Can you keep your private keys safe yourself, knowing a lost key cannot be retrieved?
Source: Guide: How to Invest in Cryptocurrency | DBS Singapore (dbs.com.sg), accessed Oct 14, 2026
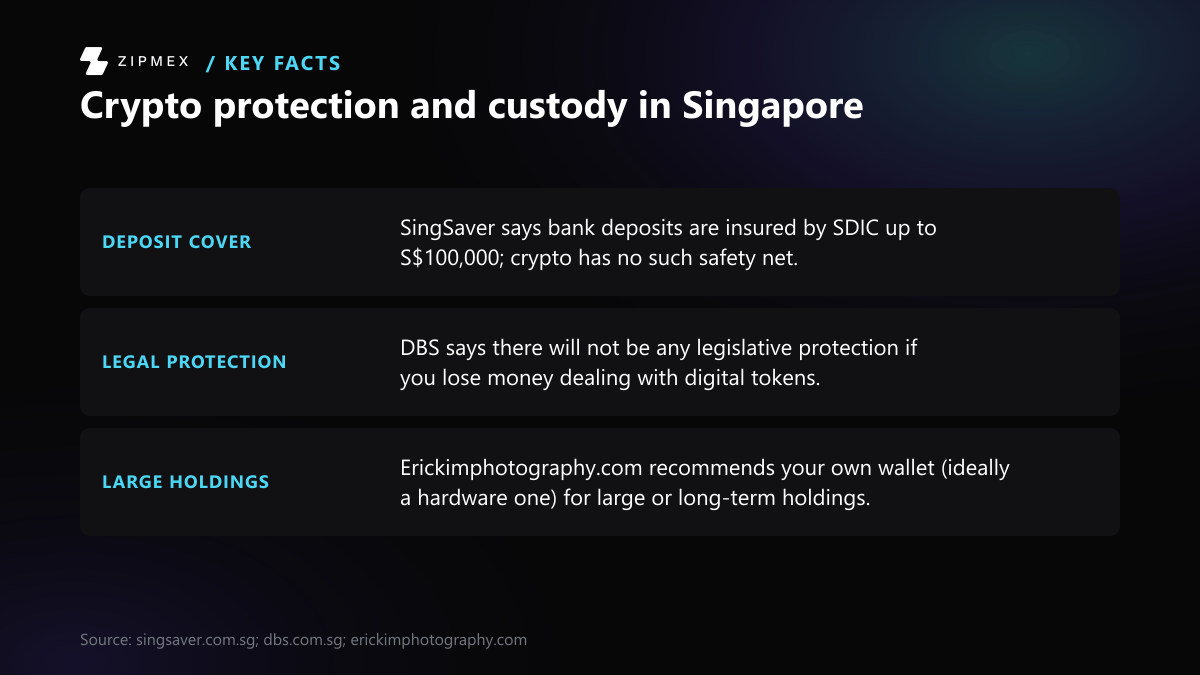
Eric Kim's guide recommends a personal wallet for large or long-term holdings, preferably a hardware one. DBS warns that a non-custodial wallet takes more effort, and lost private keys cannot be retrieved. It also says there will not be any legislative protection for losses on digital tokens.
Source: How to Buy Bitcoin in Singapore: A Comprehensive Guide (2025) - ERIC KIM (erickimphotography.com), accessed Oct 14, 2026 · Guide: How to Invest in Cryptocurrency | DBS Singapore (dbs.com.sg), accessed Oct 14, 2026DBS says bitcoin bought on an exchange is typically held by the exchange, so this is where it stays unless you move it. A commercial investment guide says an MAS-approved exchange lowers the risk of fraud, platform insolvency and unregulated operations. Eric Kim's guide advises two-factor authentication and strong, unique passwords on the exchange account.
Source: Guide: How to Invest in Cryptocurrency | DBS Singapore (dbs.com.sg), accessed Oct 14, 2026 · The Ultimate Guide to Buying Crypto in Singapore (stashaway.sg), accessed Oct 14, 2026 · How to Buy Bitcoin in Singapore: A Comprehensive Guide (2025) - ERIC KIM (erickimphotography.com), accessed Oct 14, 2026Eric Kim's guide points large or long-term holdings to a personal wallet. Until you move it, the exchange typically holds your bitcoin. An approved platform lowers some platform risks, but crypto has no deposit insurance like a bank account.
Source: How to Buy Bitcoin in Singapore: A Comprehensive Guide (2025) - ERIC KIM (erickimphotography.com), accessed Oct 14, 2026 · Guide: How to Invest in Cryptocurrency | DBS Singapore (dbs.com.sg), accessed Oct 14, 2026 · The Ultimate Guide to Buying Crypto in Singapore (stashaway.sg), accessed Oct 14, 2026 · How to Buy Cryptocurrency in Singapore (2025 Guide) (singsaver.com.sg), accessed Oct 14, 2026These are general custody trade-offs from four guides; they do not reflect any platform's terms or your own circumstances.
The most accessible and common way to buy cryptocurrencies in Singapore is to set up an account on a cryptocurrency exchange.
Step 6: Decide where to keep the bitcoin
Bitcoin you buy usually stays in the provider's custody unless you withdraw it. If it stays there, the asset-safeguarding rules below apply. If you move it to a wallet you control, you are responsible for its security. MoneySense, the national financial education programme, warns that losing your private key means losing access to your tokens.
What Singapore's rules protect
MAS guidelines and Payment Services Regulations set the following expectations for DPT service providers:
- Customer assets held on trust. Customer assets must be held in a trust account, segregated from the provider's own assets. MAS said in July 2023 that this reduces the risk of loss or misuse and helps recovery if a provider becomes insolvent.
- Cold storage. At least 90% of customer assets in trust should be kept in wallets not connected to the internet.
- No single person can move customer assets alone. Staff who control the movement of customer assets should be resident in Singapore.
- No lending or staking of retail customers' assets. Providers should not lend, stake or pledge a retail customer's assets.
- No incentives. Providers should not offer sign-up, referral or trading rewards to retail customers, or pay others such as celebrities to promote their services.
- Loss handling disclosed. Providers should state in writing how they handle customer losses caused by their own fraud or negligence.
- Complaints handling. Providers should have policies to deal with complaints fairly and within set timeframes.
- Limits on promotion. Since January 2022, guidelines (PS-G02) say providers should not advertise to the general public in Singapore, including through public-area ads, influencers and physical ATMs in public areas. Promotion is limited to the provider's own website, app and official social media accounts.
What the rules do not protect
- Price losses. MAS says its measures "cannot insulate customers from losses" from the speculative and highly risky nature of crypto trading. MoneySense says: "It is possible to lose every cent you put in cryptocurrencies."
- No help from MAS. MoneySense says MAS will not be able to help you recover losses from dealing in digital tokens that are not MAS-regulated products, even when an MAS-regulated firm provides the service.
- No deposit insurance. The Singapore Deposit Insurance Corporation (SDIC) covers Singapore-dollar deposits at member banks and finance companies, up to S$100,000 per depositor per member. Bitcoin is not a deposit, so it is outside this cover.
- Delays on insolvency. MAS warns that even with the trust rules, customers may face significant delays in getting their assets back if a provider fails.
- Overseas platforms. MoneySense notes it is hard to trace and verify the operators of trading platforms, and that if a platform fails you could lose all your money.
Tax
- GST: Since 1 January 2020, exchanging digital payment tokens for fiat currency or for other DPTs is exempt from Goods and Services Tax, according to the Inland Revenue Authority of Singapore (IRAS).
- Income tax: IRAS says profits or losses from buying and selling financial instruments, including digital tokens, are generally viewed as personal investments and are not taxable. That position is general; IRAS does not set out on that page when frequent trading would be treated as a taxable business.
Checklist before your first purchase
- Provider listed in the MAS Financial Institutions Directory with "Digital Payment Token Service".
- Name not on the MAS Investor Alert List.
- Identity verified and risk awareness assessment passed.
- Fees and custody terms read, including how the provider handles losses.
- A plan for where the bitcoin will be kept, and two-factor authentication turned on.
- An amount you can afford to lose in full.
Licences change and rules are revised, so check the directory and the latest MAS guidelines on the day you buy; this guide does not cover accredited investors, whose protections differ.