
Moving crypto from one wallet or account you own to another is not taxable under US rules. The IRS calls it "a non-taxable event, even if you receive an information return from an exchange or platform" (IRS virtual currency FAQ, Q38). There are two things to watch. If you pay the network fee in crypto, that payment is a disposal you have to report. And from 2026, a broker that receives coins you moved in does not have to report what you paid for them. If you can't show your cost basis, a later sale can look like pure profit.
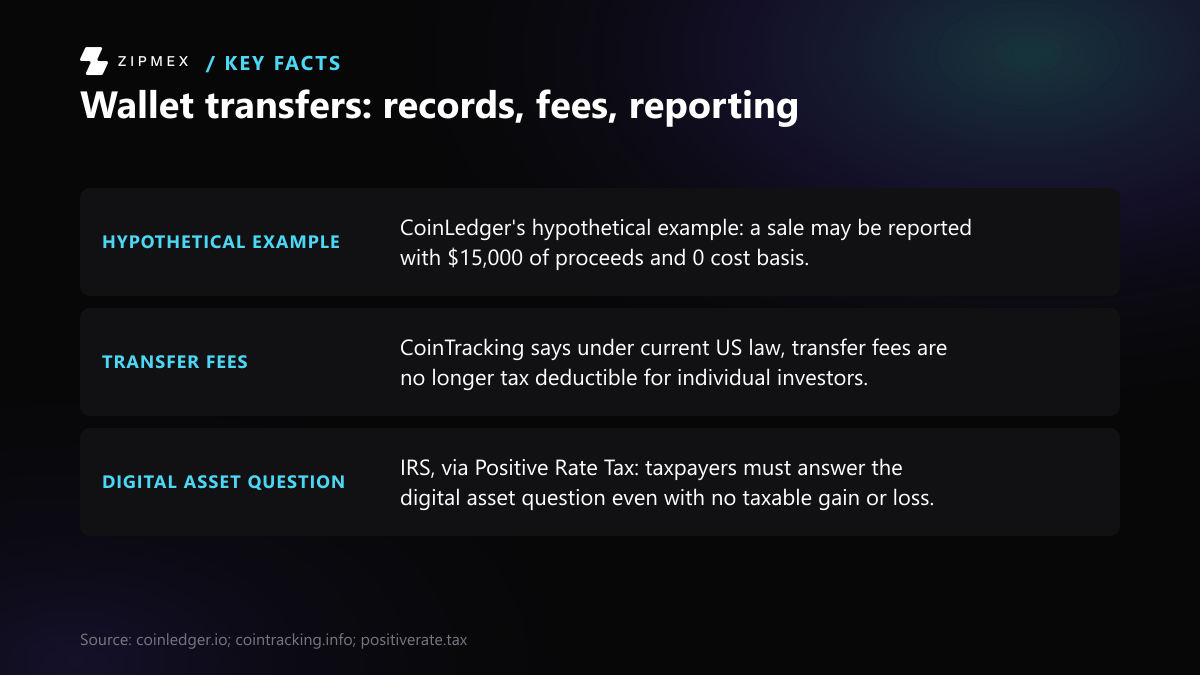

What the IRS says about self-transfers
- The move: Not taxable when both wallets belong to you (FAQ Q38).
- The digital asset question: On Form 1040, you can answer "No" if your only activity was moving digital assets between wallets or accounts you own or control. The exception is a transfer where you paid a fee in digital assets. That counts as a transaction (IRS, "Digital assets" filing page).
- Reporting: The IRS says digital asset transactions must be reported even when they produce no taxable gain or loss.
- Records: Taxpayers must "maintain records that are sufficient to establish the positions taken on tax returns" (FAQ Q46).
A transfer is not a sale. No asset leaves your ownership, so there is nothing to tax. The coins keep their original cost basis and acquisition date. That only helps you if you can prove both.
The fee is the part that counts
On a public blockchain the network fee is usually paid in the chain's own coin. The IRS lists "paying fees with them" among the ways you dispose of digital assets. Its filing page says a self-transfer becomes a transaction once the fee is paid in digital assets. In practice, you sold a small amount of crypto to pay the fee. Gain or loss on that amount runs from your basis in those units to their value when spent. One tax-software guide (CoinLedger) notes these amounts are "typically minimal". They still belong in your records.
The guides disagree on whether a self-transfer fee can be deducted or added to basis. The final digital-asset regulations (T.D. 10000, published July 9, 2024) contain rules for allocating digital asset transaction costs. On acquisitions, the IRS says basis includes "fees, commissions and other acquisition costs in U.S. dollars" (FAQ Q8).
Why records matter more from 2026
What brokers report now
- Brokers report gross proceeds on Form 1099-DA for sales on or after January 1, 2025.
- Brokers report cost basis for certain sales on or after January 1, 2026 (IRS, "Digital assets").
Basis reporting only covers "covered securities". The Form 1099-DA instructions define these as digital assets acquired after 2025 and held in the broker's custodial account until the sale. A digital asset "transferred in to the broker" is a noncovered security, and for noncovered securities the broker "is not required to report basis information". Box 12b shows the transfer-in date.
How a tax-free move becomes a reporting problem
Say you buy coins, move them to a self-custody wallet, then move them back to a broker and sell. The transfers cost you no tax. But the broker may report the sale without your basis. CoinLedger describes a hypothetical case: crypto bought for $10,000 and sold for $15,000 "may be reported with $15,000 of proceeds with 0 cost basis on Form 1099-DA." On those numbers, the gain is $5,000 with documented basis and $15,000 without it.
The fix is on your return. You list each sale on Form 8949 and carry the totals to Schedule D. You can report the correct basis there if your records support it.
Gain on your records vs. a sale reported with 0 cost basis
Enter the cost basis you can document to see the gain on CoinLedger's $15,000 sale, or enter 0 to see the gain when purchase records are missing.
| Sale price in CoinLedger's example | Cost basis you can document (0 if records are missing) | Gain measured on the sale |
|---|---|---|
| 15,000 USD | 10,000 USD | 5,000 USD |
| 15,000 USD | 0 USD | 15,000 USD |
| 15,000 USD | 15,000 USD | 0 USD |
- The sale price follows CoinLedger's hypothetical case of crypto bought for $10,000 and sold for $15,000.
- A cost basis of 0 matches the example's sale reported with $15,000 of proceeds and no purchase record.
- Fees, holding period and tax rates are left out.
A worked example from one guide's hypothetical case, not a tax calculator: it shows the gain figure only, not the tax owed.
Basis is tracked wallet by wallet
From January 1, 2025, the basis rules in Treas. Reg. §1.1012-1(j) work wallet by wallet and account by account. A single pool across all your holdings is no longer allowed. The IRS FAQ explains how to identify units:
- Specific identification: You may choose which units are sold if you can identify them and substantiate their basis (FAQ Q39). You can do this with the unit's address or with transaction records for everything held in one wallet or account (FAQ Q40).
- Default: Without identification, units are treated as sold "on a first in, first out (FIFO) basis" (FAQ Q41).
Rev. Proc. 2024-28 gave a safe harbor for assigning unused basis to specific wallets during the move to these rules.
Relief for broker-held coins, extended for 2026
In March 2026 the IRS issued Notice 2026-20, titled "Extension of temporary relief under section 1.1012-1(j)(3)(ii)". The Journal of Accountancy and KPMG report that it extends the Notice 2025-7 relief for one year. Under it, you can identify which units you are selling from broker-held coins in your own books and records, including by standing order, instead of telling the broker. It covers sales and transfers from January 1 to December 31, 2026, and does not reach coins held outside a broker's custody.
Time left until December 31, 2026 · start of day UTC
Sending to someone else is different
The non-taxable rule only covers wallets you own or control.
- Paying for goods or services with crypto is a disposal. Gain or loss runs from your basis to the value at the time of payment.
- Gifts: The recipient recognizes no income until they sell or otherwise dispose of the crypto (FAQ Q31). For computing a gain, their basis equals yours plus any gift tax paid. If they have no record of your basis, it is zero (FAQ Q32). The annual gift tax exclusion is $19,000 per recipient for 2025 and 2026 (IRS gift tax FAQ).
- Holding period: Long term means held more than one year. One year or less is short term (IRS Topic 409).
- Losses: Net capital losses reduce other income by up to $3,000, or $1,500 if married filing separately. The rest carries forward (Topic 409).
A checklist before your next transfer
- Save the purchase record for the coins you move: date, units, USD cost and fees.
- Log the transaction hash, both addresses and the time of the transfer.
- Record the fee: amount, which coin, and its USD value when paid.
- Keep one record per wallet or account, since basis is now tracked that way.
- When you sell coins you moved into a broker, check the basis on Form 1099-DA against your records before filing Form 8949.
These are US federal rules. State tax and other countries' treatment of self-transfers can differ.
