
In the United States, you report crypto every time you sell it, swap it, spend it or otherwise dispose of it. That holds even when you sold at a loss or at break-even. The IRS says digital asset transactions "must be reported whether or not they result in a taxable gain or loss." Sales and other disposals go on Form 8949, and the totals go on Schedule D. Crypto you receive as income from staking, mining or a fork goes on Schedule 1 of Form 1040. Buying crypto with dollars and holding it is not reported. Neither is moving it between your own wallets, unless you paid the network fee in crypto. Brokers began issuing Form 1099-DA for transactions on or after Jan. 1, 2025. Broker reporting of basis starts with certain transactions on or after Jan. 1, 2026.
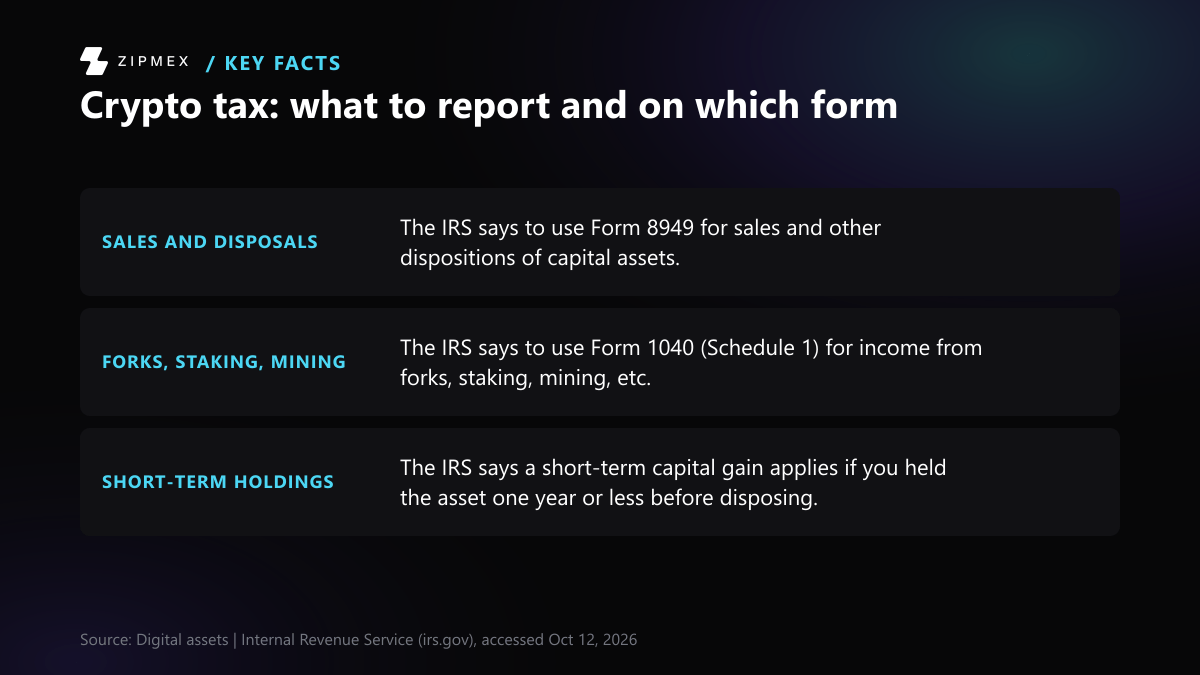

The rule everything rests on: crypto is property
The IRS's digital assets page (last reviewed Sept. 2, 2026) states: "For U.S. tax purposes, digital assets are considered property, not currency." The rest follows from that. Each time you give up a coin, you compare what you received for it with your basis, and the difference is a capital gain or loss. Basis is "generally ... the cost in U.S. dollars."
The IRS's virtual currency FAQ (last reviewed June 30, 2026) explains how that works in practice:
- Crypto-for-crypto swaps are taxable. Exchanging one virtual currency held as a capital asset for another produces a capital gain or loss (FAQ 16).
- Spending crypto is a disposal. Paying for goods or services with crypto you hold as a capital asset means you "have exchanged a capital asset for that service and will have a capital gain or loss" (FAQ 14).
- Fees raise your basis. Basis in purchased crypto includes "fees, commissions and other acquisition costs" (FAQ 8).
- Holding period sets the rate category. A gain is short-term if you held the asset for one year or less and long-term if you held it for more than one year (IRS digital assets page).
The Yes/No question on your return
Form 1040 asks every filer whether, at any time during the year, they received digital assets (as a reward, award or payment for property or services) or sold, exchanged or otherwise disposed of them. You must answer it.
The IRS lists cases where the answer can be No:
- You bought digital assets with U.S. or other real currency and did not sell them, including purchases through electronic platforms.
- You only moved digital assets between wallets or accounts you own or control. This exception does not apply if you paid a transaction fee with digital assets, because paying the fee counts as a transaction.
The question covers your whole year. One sale, swap or staking reward anywhere means the answer is Yes, even if everything else you did was buying and holding. To check whether a past transfer really went between your own addresses, you can trace it with a blockchain explorer.
Which form for which activity
| Activity | Tax treatment | Where it goes |
|---|---|---|
| Sale, swap or spend of crypto held for investment or personal use | Capital gain or loss | Form 8949, totals to Schedule D |
| Staking, mining or fork income | Ordinary income at fair market value | Form 1040, Schedule 1 |
| Crypto received as an independent contractor or from sales to customers | Business income | Schedule C (per the IRS digital assets page) |
| Crypto given as a gift | No sale by the giver | IRS points to Form 709, the gift tax return |
| Crypto received as a bona fide gift | No income until you dispose of it (FAQ 31) | Report when you later sell |
| Crypto donated to a qualifying charity | No income, gain or loss for the donor (FAQ 34) | Not a disposal for gain purposes |
| Buy with dollars and hold; move between own wallets with no crypto fee | Not a taxable event | Return question can be No |
Form 8949 now has separate boxes for digital assets
The 2025 Form 8949 instructions give crypto its own checkboxes. Short-term digital asset transactions use box G, H or I in Part I, and the instructions say "Do not use box C" for them. Long-term digital asset transactions use box J, K or L in Part II, not box F. Boxes G and J are for transactions reported to you on Form 1099-DA with basis reported to the IRS. Boxes H and K are for those where basis was not reported. You "file Form 8949 with the Schedule D" and carry the totals from Parts I and II to Schedule D.
Income from staking, mining and forks
Receiving crypto is a different event from selling it. Under Rev. Rul. 2023-14, a cash-method taxpayer who stakes and receives validation rewards includes "the fair market value of the validation rewards received" in gross income "in the taxable year in which the taxpayer gains dominion and control" over them. The same treatment applies to staking done through an exchange. Fair market value is fixed "as of the date and time the taxpayer gains dominion and control."
For forks, the FAQ says a hard fork without an airdrop produces no income. If you receive new cryptocurrency through an airdrop after a hard fork, "you will have taxable income in the taxable year you receive that cryptocurrency" (FAQs 22 to 24).
That income value becomes your basis in the coins (FAQs 12 and 13). As a result, one staking reward can show up twice on a return:
- The value at receipt goes on Schedule 1 as income.
- A later sale of the same coin goes on Form 8949. The gain or loss is measured against that value at receipt.
Crypto activity: which IRS path applies to it?
Pick one digital asset activity at a time and answer a few questions to see the IRS treatment or form for that activity.
Pick one activity you had with digital assets this tax year.
- Bought with dollars and held → A No case for this activity
- Moved coins between my own wallets → next question
- Sold or disposed of coins held for personal or investment use → Report a capital gain or loss on Form 8949
- Received coins via mining, staking, a fork, or for business goods or services → next question
Did you pay the transaction fee with digital assets?
Source: Digital assets | Internal Revenue Service (irs.gov), accessed Oct 12, 2026How did you receive the coins?
- Mining, staking or a fork → Report it on Schedule 1
- In exchange for goods or services in a business context → Ordinary income or a loss
- Some other way → This tool does not cover that activity
The IRS lists buying digital assets with U.S. or other real currency, without selling them, as a case for No on the return question. Your return answer is No only if none of your other activity this year calls for a Yes.
Source: Digital assets | Internal Revenue Service (irs.gov), accessed Oct 12, 2026Moving assets between wallets or accounts you own or control is a No case when no transaction fee was paid with digital assets. Your return answer is No only if none of your other activity this year calls for a Yes.
Source: Digital assets | Internal Revenue Service (irs.gov), accessed Oct 12, 2026The IRS excludes self-transfers where a transaction fee was paid with digital assets. Digital asset transactions must be reported whether or not they produce a taxable gain or loss.
Source: Digital assets | Internal Revenue Service (irs.gov), accessed Oct 12, 2026For assets held for personal or investment purposes, a sale or disposal produces a capital gain or loss. It goes on Form 8949, even when there is no taxable gain.
Source: Digital assets | Internal Revenue Service (irs.gov), accessed Oct 12, 2026Income from digital assets is taxable. Income from forks, staking and mining is reported on Form 1040 (Schedule 1).
Source: Digital assets | Internal Revenue Service (irs.gov), accessed Oct 12, 2026Digital assets received in exchange for goods or services in a business context are taxed as ordinary income or a loss.
Source: Digital assets | Internal Revenue Service (irs.gov), accessed Oct 12, 2026The tool resolves only mining, staking and fork income, and digital assets received in exchange for goods or services in a business context. Federal income tax returns ask a Yes or No question about digital assets, so check the IRS digital assets page for your case.
Source: Digital assets | Internal Revenue Service (irs.gov), accessed Oct 12, 2026The tool sorts one activity at a time, covers only the cases named in IRS guidance and does not calculate any tax owed.
For U.S. tax purposes, digital assets are considered property, not currency.
Form 1099-DA: what brokers report, and from when
The IRS digital assets page sets two dates:
- Gross proceeds: "Brokers must report gross proceeds for transactions effected on or after Jan. 1, 2025." This is reported on Form 1099-DA, Digital Asset Proceeds from Broker Transactions, so the first forms covered 2025 sales.
- Basis: "Brokers must report basis on certain transactions effected on or after Jan. 1, 2026."
The 2026 Form 1099-DA instructions say which transactions those are. A covered security is a digital asset "acquired after 2025" in an account where the broker provided custodial services and "held in that account until the broker effects the disposition." Anything else is noncovered. Examples include:
- a digital asset "acquired before 2026"
- one "transferred in to the broker providing custodial services"
For noncovered assets, "the broker is not required to report basis information," although it may do so voluntarily.
In practice:
- Coins bought before 2026. If you sell them in 2026, the form may show proceeds with no basis. You supply the basis from your own records.
- Coins moved onto a platform from a self-custody wallet. These are noncovered even if you bought them later.
- Small broker thresholds. The 2026 instructions also set reporting thresholds for brokers: $10,000 a year for designated sales of qualifying stablecoins, and $600 a year for specified NFTs and for payment-processor sales. These thresholds only decide whether the broker files a 1099-DA. They do not change your own duty to report every transaction.
Two related developments:
- Backup withholding. Notice 2025-33 (IR-2025-67, June 12, 2025) extends transition relief from backup withholding liability and penalties to brokers for digital asset sales effected in 2026, with limited relief for 2027.
- DeFi broker rule. The separate rule that would have treated certain decentralised finance platforms as brokers was overturned. The President signed a Congressional Review Act resolution, H.J.Res.25, on April 10, 2025, according to the House Ways and Means Committee.
Basis is tracked wallet by wallet
Since Jan. 1, 2025, final broker regulations require basis to be tracked separately for each wallet or account. Rev. Proc. 2024-28 (Internal Revenue Bulletin 2024-31) gives a safe harbor for the switch. You may rely on "any reasonable allocation" of unattached basis to the wallets or accounts that held the same number of remaining units, based on your records. The allocation "must be made as of January 1, 2025."
What this means for records:
- Keep acquisition records per wallet. Note the date, units, dollar cost and fees for each wallet or account.
- Keep your Jan. 1, 2025 allocation. If you used the safe harbor, keep the record of how you allocated basis.
- Expect gaps on coins moved between platforms. A broker cannot see their history, so it will often report no basis for them.
A practical sequence before filing
- List every wallet and account you used during the year.
- Mark each event as one of these: buy and hold, self-transfer, self-transfer with a crypto fee, disposal (sale, swap or spend), income (staking, mining, airdrop, payment) or gift.
- For each disposal, match the proceeds to basis from the same wallet and note whether you held the asset for more than one year.
- Compare your list with any Form 1099-DA you received, and check which Form 8949 box (G to L) each line belongs in.
- Record income events at fair market value on the date and time you gained control. That value becomes the basis for a later sale.
- Answer the Form 1040 digital asset question for the whole year.
Limitations
This article covers federal IRS rules only. It does not cover state tax, tax rates, business or accrual-method taxpayers, or non-US rules, and it is not tax advice. Check details with the IRS or a tax professional.
