
An order book is the live list of every buy and sell order still waiting in one market. A trade happens when an incoming order meets a waiting order on the other side at a price both accept. On most order books the best price is filled first. When two orders share a price, the one that arrived first is filled first. This rule is called price-time priority, and the trading firm Optiver describes it in these terms. A market order takes the best prices already in the book. A limit order that cannot fill at once joins the book and waits. The same structure is often called a central limit order book, or CLOB.
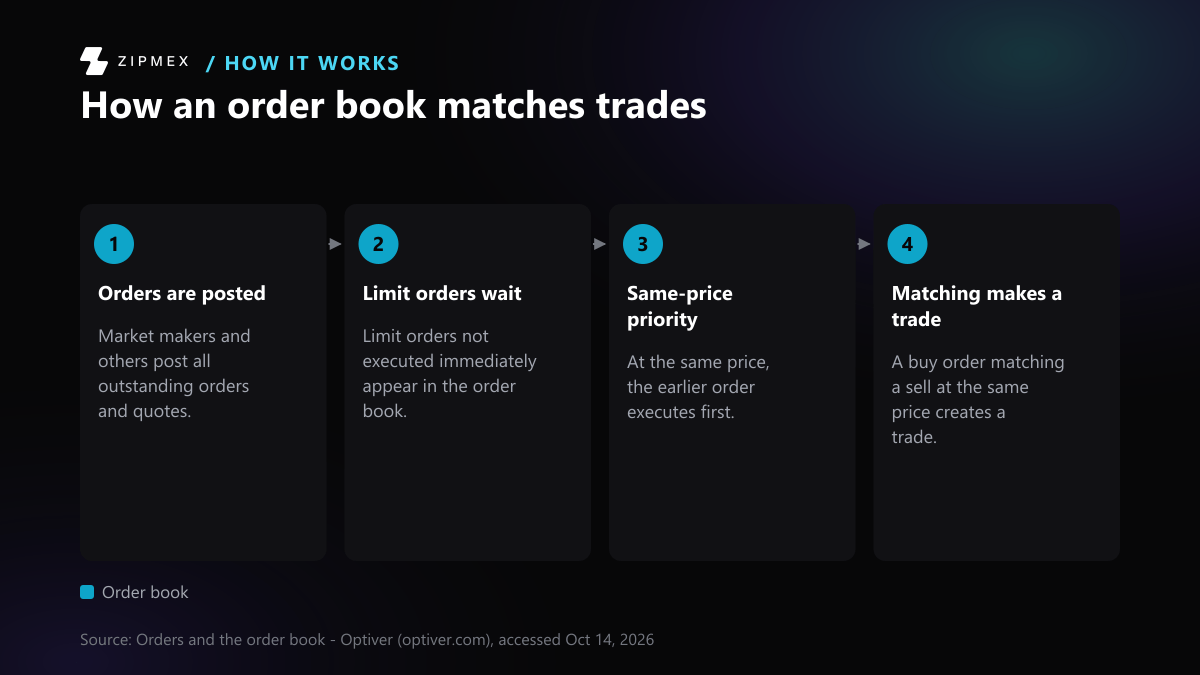

Optiver's definition: "The order book lists all outstanding orders and quotes in a particular financial instrument posted by market makers and other market participants."
Why the order book matters
The order book is not only a crypto structure. A widely cited paper by Gould, Porter, Williams, McDonald, Fenn and Howison (arXiv:1012.0349) says limit order books "match buyers and sellers in more than half of the world's financial markets." Crypto venues that run an order book use the same building blocks as stock and futures markets: bids, asks, priority rules and order types.
How the book is laid out
The book has two sides:
- Bids: buy orders, with the highest price at the top.
- Asks (also called offers): sell orders, with the lowest price at the top.
The best bid and the best ask meet in the middle of the screen. The bid-ask spread is the gap between them. Optiver defines it as the lowest ask minus the best bid. Optiver also says traders can judge liquidity by looking at the bid and ask volume.
Market depth goes further than the top of the book. The cryptoanalysis.ai explainer (17 July 2026) defines it as "how much volume rests at each price level across the entire book, not just at the best bid or ask."
How a trade is matched
Price first, then time
Optiver puts the core rule in one line: "When a buy order matches at the same price with a sell order, then a trade is born." The matching engine fills the best-priced resting order first, no matter when it arrived. If several orders sit at that price, the earliest one goes first.
Not every book uses pure time priority
Price-time priority, also called FIFO (first in, first out), is common but not universal. CME Group's Globex documentation describes FIFO as resting orders "matched in timestamp order only." It also describes a pro-rata step, which "fills by proportion of the working order quantity compared to the entire quantity present at the price level." Under pro rata, larger resting orders get a larger share of each fill. The rule a given book uses changes the incentives for the traders who post orders on it.
A worked example
These numbers are made up for illustration. Say the ask side shows:
| Ask price | Size |
|---|---|
| 100.10 | 2 |
| 100.20 | 3 |
A market order to buy 4 units fills 2 at 100.10 and the remaining 2 at 100.20, an average of 100.15. The best ask on screen was 100.10. The 0.05 difference is slippage. Cryptoanalysis.ai defines slippage as "the difference between the price shown at order entry and the actual average fill price." A large order eats through several price levels, so a thin book means more slippage.
Market order vs limit order
Which risk does each order type leave you with: an uncertain price or an uncertain fill?
| Order type | Price | Execution | Place in the order book | Source |
|---|---|---|---|---|
| Market order | The best price currently available in the order book | Normally ensures execution, but not the price received | Takes an existing price from the book | Source: Orders and the order book - Optiver (optiver.com), accessed Oct 14, 2026 |
| Limit order | A maximum price to pay or a minimum price to receive | Not assured | Appears in the book if not executed immediately | Source: Orders and the order book - Optiver (optiver.com), accessed Oct 14, 2026 |
These are Optiver's general definitions; order options and rules differ by platform, and the table does not predict fill prices.
The order book lists all outstanding orders and quotes in a particular financial instrument posted by market makers and other market participants.
Market orders and limit orders
| Market order | Limit order | |
|---|---|---|
| Price | Best price currently in the book | Set maximum to pay or minimum to receive |
| Fill | Normally fills | Not assured |
| Place in the book | Takes liquidity already resting there | Rests in the book if it cannot fill at once |
Optiver defines a market order as an order "to buy or sell a stock at the best price currently available in the order book." It defines a limit order as one that "specifies a maximum price to be paid or a minimum price to be received." The US broker regulator FINRA describes a limit order as one "to buy or sell a security at or better than a specified price." It warns that with market orders you "might not get the price you saw or were originally quoted, especially in fast-moving markets."
The two types trade one risk for another. A market order takes on price uncertainty to get a fill. A limit order takes on fill uncertainty to protect the price. If a limit buy is priced at or above the best ask, it executes straight away against the resting asks, up to its limit. Only the part that does not fill joins the book.
Stop, stop-limit and iceberg orders
- Stop order. FINRA describes this as an order to buy or sell "once the price of the security reaches a specified price." Once triggered it behaves like a market order, so the fill price can differ from the stop price.
- Stop-limit order. Here "your stop order is designed to trigger the activation of a limit order" (FINRA). It controls the price but may not fill.
- Iceberg order. Only part of the size is shown in the book. Optiver explains: "Once the displayed peak of the iceberg is executed, it is refreshed with part of the hidden quantity." Because of icebergs, the visible book can understate the real size waiting at a price.
Not every venue offers every order type, and the exact rules differ between venues.
Who fills the book, and when it thins out
Optiver says a market maker, "also called a liquidity provider, is a firm or individual that continuously provides quotes" on both sides. What a liquidity provider does is covered in a separate explainer.
That supply shifts with conditions. According to cryptoanalysis.ai, market makers compete with tight spreads and thick books when markets are calm. In volatile periods they widen quotes or pull resting orders. Resting orders can also be cancelled at any moment. In the explainer's words, "The order book shows intent, not commitment." So slippage estimates taken in a quiet market can understate costs during stress.
What different data feeds show
Market-data vendor CoinAPI groups order book data into three levels:
- Level 1: "only the best bid/ask prices and volumes."
- Level 2: "aggregated quantities at multiple price levels."
- Level 3: "every individual order with unique IDs, timestamps, and full lifecycle tracking."
Most trading screens show something close to Level 2. Level 3 data exists only where a venue publishes per-order data.
Practical checks before placing an order
- Look at the spread. A wide gap between best bid and best ask is a cost you pay just for crossing the book.
- Compare your size with the depth. If your order is bigger than what rests at the best price, expect a fill across several levels, as in the example above.
- Pick the risk you accept. A market order puts the price at risk. A limit order puts the fill at risk.
- Read the venue's own rules. Matching rules (FIFO or pro rata), stop triggers and supported order types vary.
Limitations: the definitions here come from general explainers, a regulator's investor page and futures-exchange documentation, not from any single crypto venue's rulebook, and they do not predict fill prices on any platform.
